Crypto Tax Advice in Portugal
Crypto tax advice in Portugal helps individuals who bought, sold, exchanged or received crypto-assets establish their Portuguese tax position. We reconstruct each holding period for the IRS return, because qualifying gains and losses are excluded when the assets were held for at least 365 days.
First conversation free Reply within one business day
Who Needs Crypto Tax Services in Portugal
- You bought, sold, exchanged or received crypto-assets and need the Portuguese tax treatment tested against your records.
- You received remuneration in crypto-assets and need the timing rule for later disposal reviewed.
- You mine, issue or validate crypto-assets and need the Category B activity and simplified-regime treatment assessed.
- You have Portuguese and foreign wallets, exchanges or income and need the reporting and return position prepared together.
The scope is Portuguese crypto tax treatment, income and reporting. A crypto-asset service provider's authorisation or permission status is a separate matter.
What's Included in Crypto Tax Services
You get a quote in writing before any work starts.
- Asset classification. A certified accountant identifies whether the asset is a crypto-asset, a security, a unique non-fungible asset or another category from the available facts.
- Income and disposal analysis. A certified accountant applies the relevant CIRS category to remuneration, disposals, exchanges and received assets.
- Holding-period review. A certified accountant reconstructs acquisition and disposal dates to test the 365-day rule.
- Crypto-for-crypto review. A certified accountant records the acquisition value carried forward when the CIRS conditions apply to a crypto-asset consideration.
- Mining and activity analysis. A certified accountant reviews issuance, mining and consensus validation as potential Category B activities.
- Return preparation. A certified accountant prepares the agreed Portuguese IRS return and supporting schedules for submission to AT.
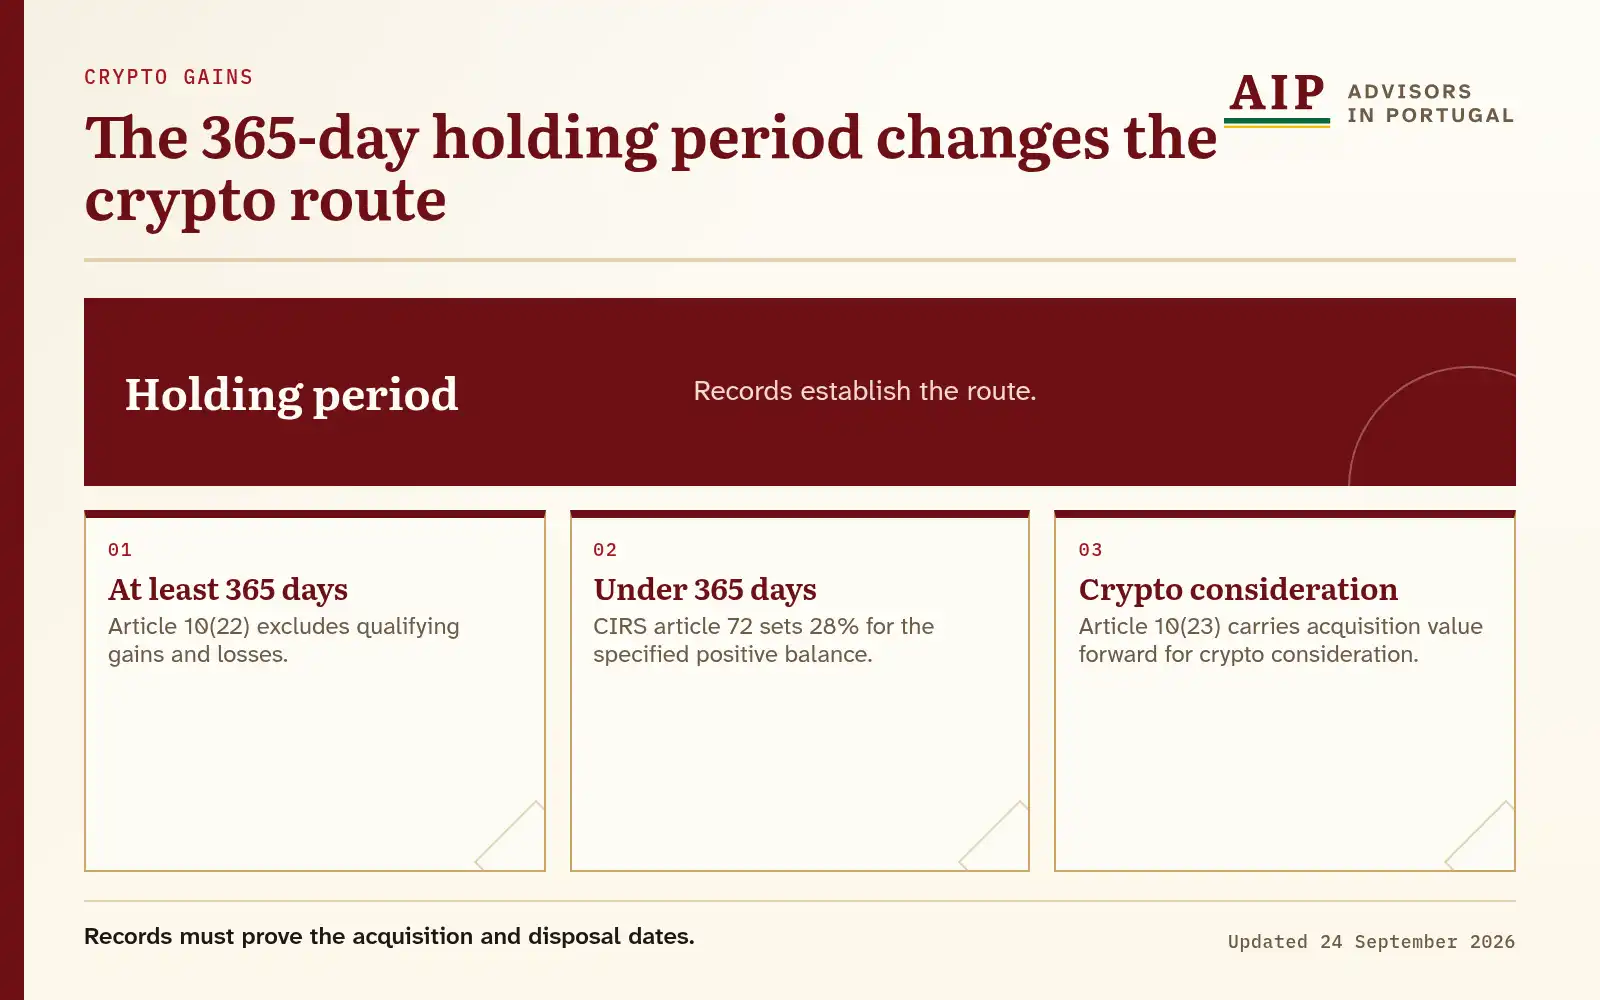
Diagram text version
Article 10(22) excludes qualifying gains and losses. CIRS article 72 sets 28% for the specified positive balance. Article 10(23) carries acquisition value forward for crypto consideration.
What You'll Need to Provide
- Residence and tax-year facts
- Your Portuguese residence position, tax year, NIF, prior returns and any other country connected with the activity.
- Wallet and exchange exports
- Transaction exports, wallet addresses, exchange statements and account histories for the periods under review.
- Acquisition and disposal records
- Dates, quantities, values, fees, counterparties and transaction identifiers for purchases, sales and exchanges.
- Received-asset records
- Employment, services, staking, rewards or other records showing how crypto-assets were received.
- Activity records
- Mining, issuance, validation, equipment, energy, service and business records when the activity is habitual or organised.
- Foreign-tax and filing records
- Foreign tax statements, Portuguese filings, AT notices and payment evidence connected with the crypto position.
How Crypto Tax Services Are Handled in Portugal
A certified accountant prepares the agreed crypto return for submission to the Autoridade Tributária e Aduaneira and flags accounting, business-income and cross-border questions along the way.
-
Establishing the Residence and Tax Year
A certified accountant records the relevant tax year, residence facts, NIF and Portuguese or foreign filing history.
-
Classifying the Crypto Assets and Activity
A certified accountant maps each asset and activity to the CIRS category supported by the transaction and business records.
-
Reconstructing the Transaction History
A certified accountant reconciles wallet, exchange and received-asset records into an acquisition, disposal and income schedule.
-
Applying the Holding-Period and Rate Rules
A certified accountant tests the 365-day rule, the applicable rate, aggregation and simplified-regime treatment against the evidence.
-
Preparing the Crypto Tax Schedules
The schedules and supporting evidence needed for the agreed Portuguese IRS return are prepared.
-
Preparing the Agreed IRS Return
A certified accountant prepares the agreed crypto return for submission to the Autoridade Tributária e Aduaneira.
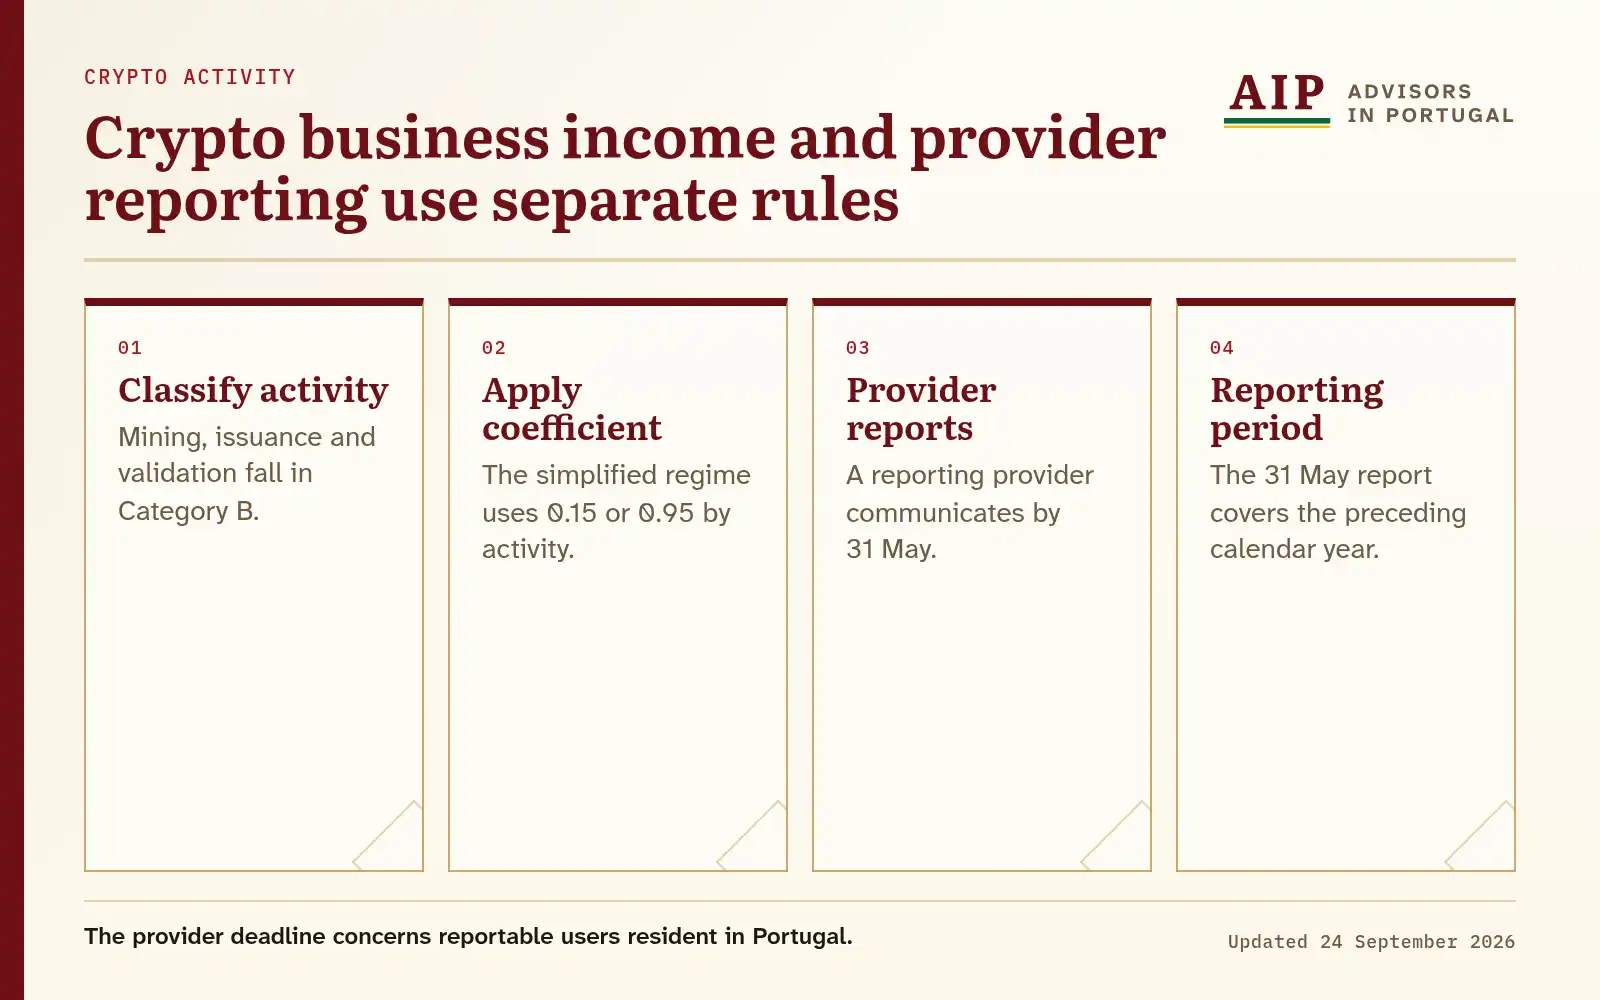
Diagram text version
Mining, issuance and validation fall in Category B. The simplified regime uses 0.15 or 0.95 by activity. A reporting provider communicates by 31 May. The 31 May report covers the preceding calendar year.
Timing and Possible Delays
Set by the tax year and transaction records
The work is planned around the tax year, wallet exports, exchange statements, asset classifications and activity records.
What delays it
The work takes longer when an exchange export is incomplete, wallets cannot be reconciled, received-asset records are missing or the activity spans several countries and tax years.
What to prepare now
Organise your residence, wallet, exchange, activity, foreign-tax and prior-filing records before the work begins.
Wallet Records, Classification and Reporting
The wallet and activity ledger
A certified accountant labels each line by acquisition, disposal, remuneration, mining, issuance or validation so the CIRS category rests on an identifiable transaction history. A certified accountant then separates habitual activity from isolated transactions before applying the relevant reporting treatment.
The evidence for the holding period
A certified accountant links the original acquisition to each later disposal or crypto-for-crypto exchange before applying the 365-day rule and any carried-forward value. You should preserve the export metadata that shows the wallet or exchange source when a transaction history spans multiple platforms.
The provider report and your return
Provider statements are stored with the wallet ledger, and the records that support your own Portuguese IRS return are marked. A certified accountant then checks the provider data against your income and disposal schedule before the agreed return is prepared.
Set out your crypto tax position
State where you lived, which assets and wallets you used, how you received or disposed of crypto-assets and which filings already exist.
Common questions
How does Portugal tax remuneration received in crypto-assets?
Which crypto-asset disposals fall under Article 10?
What is the 365-day crypto holding rule?
What rate applies to crypto-asset gains?
Can crypto gains be aggregated with other income?
How does Portugal tax mining or validation?
Which simplified-regime coefficient applies to crypto activity?
How are crypto-for-crypto exchanges recorded?
When must a crypto-asset service provider report to AT?
How is my crypto tax return handled?
How the Crypto Tax Service Works
-
One point of contact for the whole case.
One contact covers the accounting, business-income and cross-border specialists the crypto tax work touches.
-
English or Portuguese.
English or Portuguese, whichever you are most comfortable in.
-
A quote in writing before work starts.
You get a quote in writing before any work starts. You are told plainly if your case is outside the service.
What clients say about working with our founding team
Reviews from clients who worked with our founding team at their previous firm.
1–3 of 13
-
Samuel T. Google review, c. 2024 “I decided to partner with [the firm] for the establishment of multiple subsidiary companies in different jurisdictions. The entire process was streamlined and I felt well-supported throughout. I continue to collaborate with them in these countries and would highly recommend their services!”
-
Joseph V. Google review, c. 2016 “Our company has used the services of [the firm] for the purpose of conducting a thorough Due Diligence on a number of mining titles, the preparation of complicated, cross jurisdictional purchase contracts as well as the incorporation of a local subsidiary... All work was completed to a high standard, on budget and on time.”
-
Joe M. Google review, c. 2022 “Expanding our operations in Colombia has been challenging to say the least... Their years of experience, professionalism and most importantly their patience(!) have been vital to our success... [They] honestly feel like an extension of our team.”
-
Amy D. Google review, c. 2019 “The team at [the firm's Ecuador office] has helped streamline our accounting and other administrative tasks flawlessly between two countries and between staff and vendors in multiple locations... Highly recommended.”
-
Kunal D. Google review, c. 2022 “[The founder and the team] have always demonstrated a prudent, distinct and rapid ways of resolving issues and can tailor the needs as per our requirements... Their quick and error free approach has been instrumental.”
-
Julian A. Google review, c. 2022 “I emailed them and it was not more than a couple of hours when they emailed me back... I cannot be more satisfied with how [the firm] handled the process of registering my business in the country.”
-
George T. Google review, c. 2016 “The team is knowledgable, experienced and extremely professional, whilst being very approachable and friendly. If you want to do business in Mexico, there is no one better, in my opinion.”
-
Priscila O. Google review, c. 2024 “The group is fantastic! Contact [the founder] and the group if you require assistance with the incorporation of your small business!!!”
-
Christopher W. Google review, c. 2015 “I was pleased to find all the staff that worked with us to be not only attentive and responsive, but aware of our specific needs. Although we were unable to proceed due to our own financial situation, it did not stop [the firm], and more specifically... [the founder], from trying to find ways to make the effort work.”
-
Hassan J. Google review, c. 2024 “Very much appreciated the opportunity to speak directly with [the founder] when I reached out. The information provided was clear and in contact. Highly recommended!!!”
-
Simon T. Google review, c. 2020 “A great service. Very efficient. [The founder] was professional and organised everything we needed”
-
Janete C. Google review, c. 2024 “Thanks for everything... An excellent experience and highly recommended!!!”
-
Sean W. Google review, c. 2025 “[The founder] and Team [at the firm] provided our company quick, accurate & relevant advice to our company for a proposal in Costa Rica. Recommend their services to anyone...”
Text in [brackets] replaces names used in the reviews. The original reviews are on Google.
Contact us
Your request is in
Every request is read in house. The requirements are assessed, and a reply by email sets out the appropriate next steps.
Every enquiry is read in house, and the aim is a reply within one business day.
The information on this page is checked against official sources and reviewed regularly. It is corrected when the law or official guidance changes, as the Editorial Standards describe.