Corporate Tax Advisors in Portugal
A corporate tax advisor in Portugal reviews the IRC and state-surcharge position of companies and groups with Portuguese tax obligations. We check whether the company qualifies for 15% on its first EUR 50,000 and whether taxable profit passes the EUR 1.5 million surcharge threshold.
First conversation free Reply within one business day
Who Needs a Corporate Tax Advisor in Portugal
- Your company needs its 2026 IRC rate, state surcharge and autonomous-taxation exposure calculated from its accounts.
- Your group expects dividends, a share disposal or a cross-border payment and needs the relief conditions checked before the transaction.
- Modelo 22, IES/DA or related tax work needs reconciling with your company's accounts.
- Your company is considering Madeira or another regional position and needs eligibility reviewed without assuming a tax outcome.
Your business needs bookkeeping or payroll if its tax position is already settled.
What's Included in Corporate Tax Compliance
You get a quote in writing before any work starts.
- IRC position. A certified accountant calculates the rate and taxable-income position for the relevant period.
- Surcharge review. A certified accountant checks the state-surcharge threshold and the municipal position that applies to the company's facts.
- Autonomous-taxation review. A certified accountant identifies the relevant expense categories and tests the loss-period uplift under Article 88 of the CIRC.
- Participation-exemption analysis. A certified accountant checks dividends and qualifying participations against Article 51 of the CIRC.
- Cross-border payment review. A certified accountant checks treaty or domestic-law relief and the proof needed before the payment.
- Corporate filing support. A certified accountant reconciles Modelo 22 and IES/DA work with the company's accounts and filing calendar.
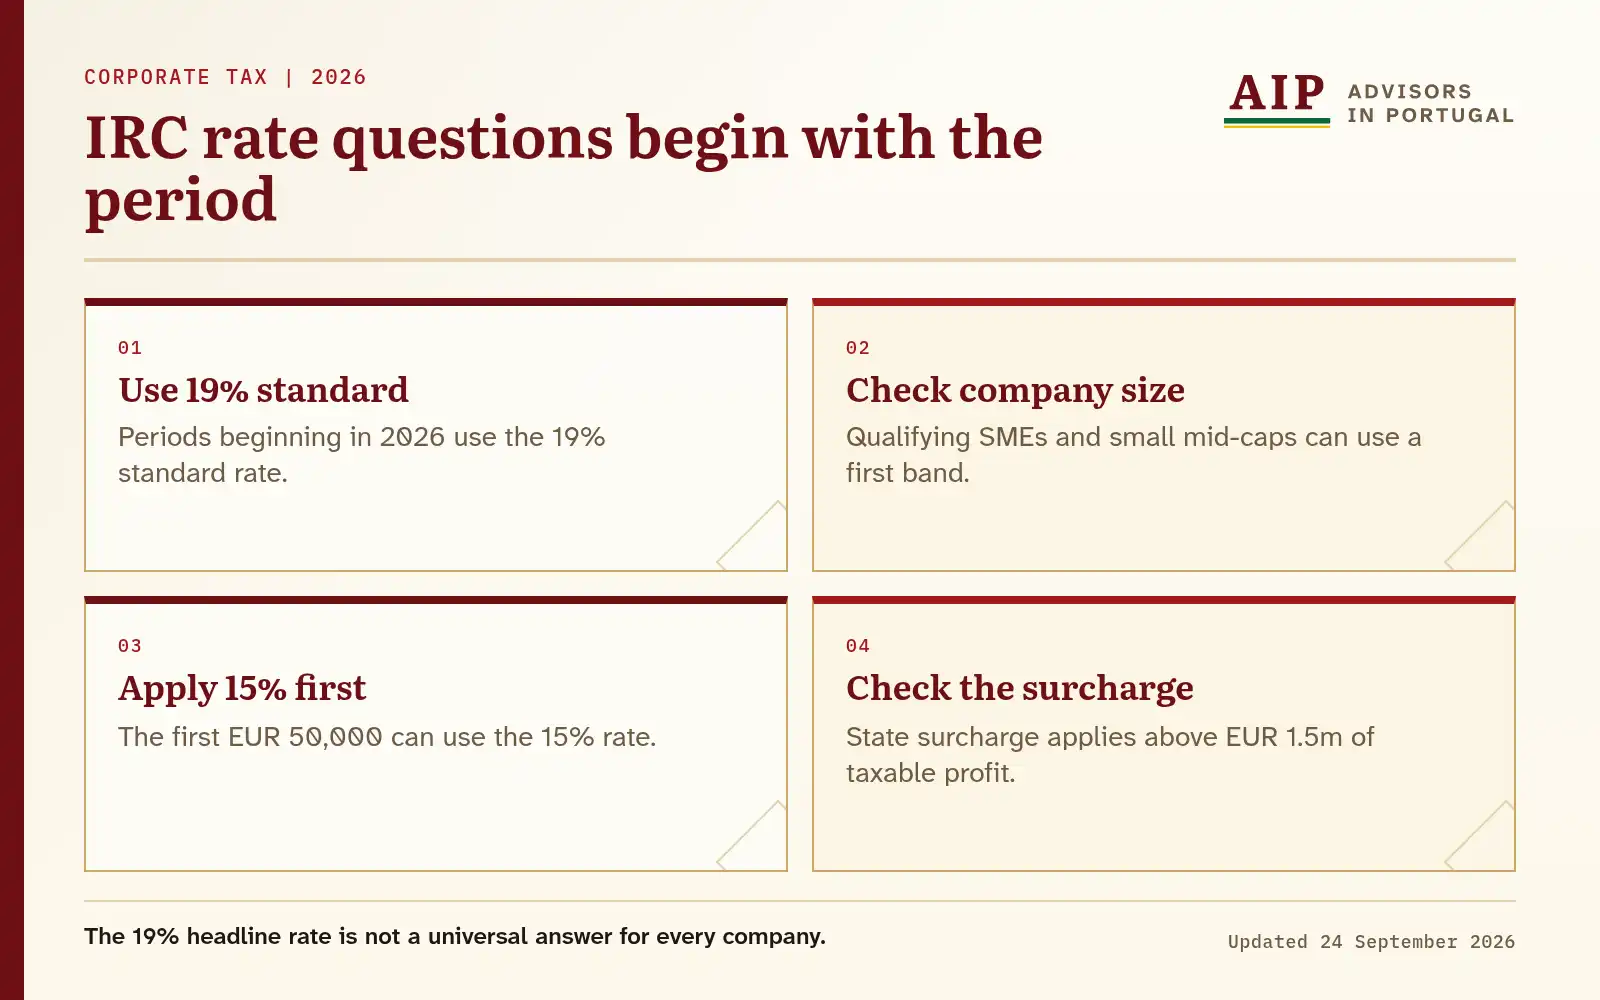
Diagram text version
Use 19% for the 2026 standard rate. Check company size. Apply 15% to the first EUR 50,000 when eligible. Check the EUR 1.5m surcharge threshold.
What Your Company Needs to Provide
- Company and group structure
- The Portuguese entity, shareholders, subsidiaries and countries involved.
- Accounts and tax period
- Current accounts, prior returns and the start and end dates of the tax period under review.
- Transaction documents
- Available agreements, invoices and calculations for the dividend, disposal, financing or other transaction.
- Expense detail
- The expense categories that may require an autonomous-taxation review.
- Tax-loss history
- Available assessments and returns showing the losses the company expects to use.
- Non-resident evidence
- The recipient's legal form, residence and available treaty or domestic-law documentation.
How Corporate Tax Compliance in Portugal Works
A certified accountant works with the Autoridade Tributária e Aduaneira on the relevant filings and reconciles the tax position with your company's accounts, transactions and shareholder structure.
-
Company and tax-period review
A certified accountant confirms the entity, tax period, group structure and issue covered by the engagement.
-
IRC rate calculation
A certified accountant applies Article 87 of the CIRC to the company's taxable-income position.
-
State surcharge and autonomous taxation
A certified accountant checks the state-surcharge threshold and the expenses governed by Article 88 of the CIRC.
-
Participation exemption and loss review
A certified accountant tests the relevant dividend, participation and available-loss position against the applicable conditions.
-
Cross-border and regional review
A certified accountant checks withholding relief and any regional regime against the company, recipient and transaction facts.
-
Modelo 22 and IES/DA filing plan
A certified accountant sets out the calculations, documents and filing work needed for the relevant deadlines.
Timing and Filing Calendar
Set by the tax period and scope
The work is planned around the transaction, accounts, filing period and required documents.
What delays it
The work takes longer if accounts are incomplete, group documents are missing, the recipient's residence evidence is unavailable or a regional eligibility question needs further analysis.
What to prepare now
Your company gathers its structure chart, accounts, prior returns, transaction documents and non-resident evidence before the work begins.
Rates, Reliefs and Filing Obligations
IRC rates and the state surcharge
Article 87 of the CIRC sets the standard IRC rate at 19% for 2026, 18% for 2027 and 17% from 2028. The same article sets a 15 percent rate on the first EUR 50,000 of taxable income for eligible SMEs and small mid-caps. Article 87-A applies the state surcharge above EUR 1.5 million of taxable profit, and a certified accountant verifies the brackets for the company’s period.
Autonomous taxation
Article 88 of the CIRC taxes specified expense categories separately from the headline IRC calculation. It sets a 10% rate for representation expenses, uses different rates for vehicles and undocumented expenses, and increases relevant rates by 10 percentage points in loss cases. A certified accountant maps the company’s expenses to the current categories before calculating the amount.
Participation relief and filing dates
Article 51 of the CIRC generally requires a participation of at least 10 percent, or an acquisition cost of at least EUR 20 million, held for one year, together with its other conditions. The Autoridade Tributária e Aduaneira’s 2026 fiscal calendar sets 30 June 2026 for Modelo 22 and 15 July 2026 for IES/DA for a calendar-year company. A certified accountant reconciles the relief analysis with the accounts and filing work.
Put the tax rules against your company's figures
Describe the company, tax period, transaction and filing issue. A certified accountant then reviews the IRC, surcharge, relief and compliance position.
Common questions
What is the corporate tax rate in Portugal in 2026?
Does Portugal have a reduced corporate tax rate for smaller companies?
When does the state surcharge apply?
Does a municipal surcharge apply to every company at the same rate?
What is autonomous taxation?
When can a dividend qualify for the participation exemption?
When are Modelo 22 and IES/DA due for a calendar-year company in 2026?
Can a treaty reduce withholding on a payment to a non-resident?
Can a Madeira company assume a particular corporate tax result?
How is corporate tax work handled?
What to Expect
-
One team for the whole case.
The tax, accounting, corporate and cross-border questions are all handled by the same team.
-
English or Portuguese.
English or Portuguese, whichever you are most comfortable in.
-
A written quote before work starts.
You get a quote in writing before any work starts. The reply says so plainly if the case is not something the service covers.
What clients say about working with our founding team
Reviews from clients who worked with our founding team at their previous firm.
1–3 of 13
-
Samuel T. Google review, c. 2024 “I decided to partner with [the firm] for the establishment of multiple subsidiary companies in different jurisdictions. The entire process was streamlined and I felt well-supported throughout. I continue to collaborate with them in these countries and would highly recommend their services!”
-
Joseph V. Google review, c. 2016 “Our company has used the services of [the firm] for the purpose of conducting a thorough Due Diligence on a number of mining titles, the preparation of complicated, cross jurisdictional purchase contracts as well as the incorporation of a local subsidiary... All work was completed to a high standard, on budget and on time.”
-
Joe M. Google review, c. 2022 “Expanding our operations in Colombia has been challenging to say the least... Their years of experience, professionalism and most importantly their patience(!) have been vital to our success... [They] honestly feel like an extension of our team.”
-
Amy D. Google review, c. 2019 “The team at [the firm's Ecuador office] has helped streamline our accounting and other administrative tasks flawlessly between two countries and between staff and vendors in multiple locations... Highly recommended.”
-
Kunal D. Google review, c. 2022 “[The founder and the team] have always demonstrated a prudent, distinct and rapid ways of resolving issues and can tailor the needs as per our requirements... Their quick and error free approach has been instrumental.”
-
Julian A. Google review, c. 2022 “I emailed them and it was not more than a couple of hours when they emailed me back... I cannot be more satisfied with how [the firm] handled the process of registering my business in the country.”
-
George T. Google review, c. 2016 “The team is knowledgable, experienced and extremely professional, whilst being very approachable and friendly. If you want to do business in Mexico, there is no one better, in my opinion.”
-
Priscila O. Google review, c. 2024 “The group is fantastic! Contact [the founder] and the group if you require assistance with the incorporation of your small business!!!”
-
Christopher W. Google review, c. 2015 “I was pleased to find all the staff that worked with us to be not only attentive and responsive, but aware of our specific needs. Although we were unable to proceed due to our own financial situation, it did not stop [the firm], and more specifically... [the founder], from trying to find ways to make the effort work.”
-
Hassan J. Google review, c. 2024 “Very much appreciated the opportunity to speak directly with [the founder] when I reached out. The information provided was clear and in contact. Highly recommended!!!”
-
Simon T. Google review, c. 2020 “A great service. Very efficient. [The founder] was professional and organised everything we needed”
-
Janete C. Google review, c. 2024 “Thanks for everything... An excellent experience and highly recommended!!!”
-
Sean W. Google review, c. 2025 “[The founder] and Team [at the firm] provided our company quick, accurate & relevant advice to our company for a proposal in Costa Rica. Recommend their services to anyone...”
Text in [brackets] replaces names used in the reviews. The original reviews are on Google.
Contact us
Your request is in
Every request is read in house. The requirements are assessed, and a reply by email sets out the appropriate next steps.
Every enquiry is read in house, and the aim is a reply within one business day.
The information on this page is checked against official sources and reviewed regularly. It is corrected when the law or official guidance changes, as the Editorial Standards describe.