Statutory Audit Support in Portugal
Statutory audit support in Portugal tests whether a company exceeds two of three CSC Article 262(2) thresholds in two consecutive years. We prepare the appointment records for an OROC-qualified statutory auditor, who signs the audit.
First conversation free Reply within one business day
Who Needs Audit Services in Portugal
- Your company may exceed the statutory-audit thresholds and needs the two-year test applied to its figures.
- Your group prepares consolidated accounts and needs the parent, subsidiary and exemption rules checked.
- You need an OROC-qualified statutory auditor or the audit-report signature route.
- Your company needs annual accounts, commercial registration and SNC reporting obligations placed in sequence.
Bookkeeping cleanup, management accounts and an assurance conclusion outside the statutory-audit professional route are outside the offer.
What's Included in Portuguese Audit Support
The service defines the threshold, appointment, evidence and reporting work that a Portuguese audit engagement requires.
- Statutory-audit trigger. CSC Article 262(2) requires a statutory audit when two of its three thresholds (balance-sheet total, net sales and other income, average headcount) are exceeded in two consecutive years, subject to the current official text for the entity type.
- OROC signatory. The statutory audit and certification are performed and signed within the Ordem dos Revisores Oficiais de Contas (OROC) framework.
- Independence and conflicts. The OROC statute sets independence, ethics and incompatibility rules that the auditor confirms before appointment.
- Annual accounts. A specialist maps the three-month approval period, the five-month consolidated or equity-method extension and commercial registration.
- Group reporting. A specialist tests parent control, consolidated-account preparation and the small-group exemption conditions under the SNC.
- SNC and evidence. The engagement file holds the mandatory SNC framework, audit evidence and OROC Article 76's minimum five-year conservation period.
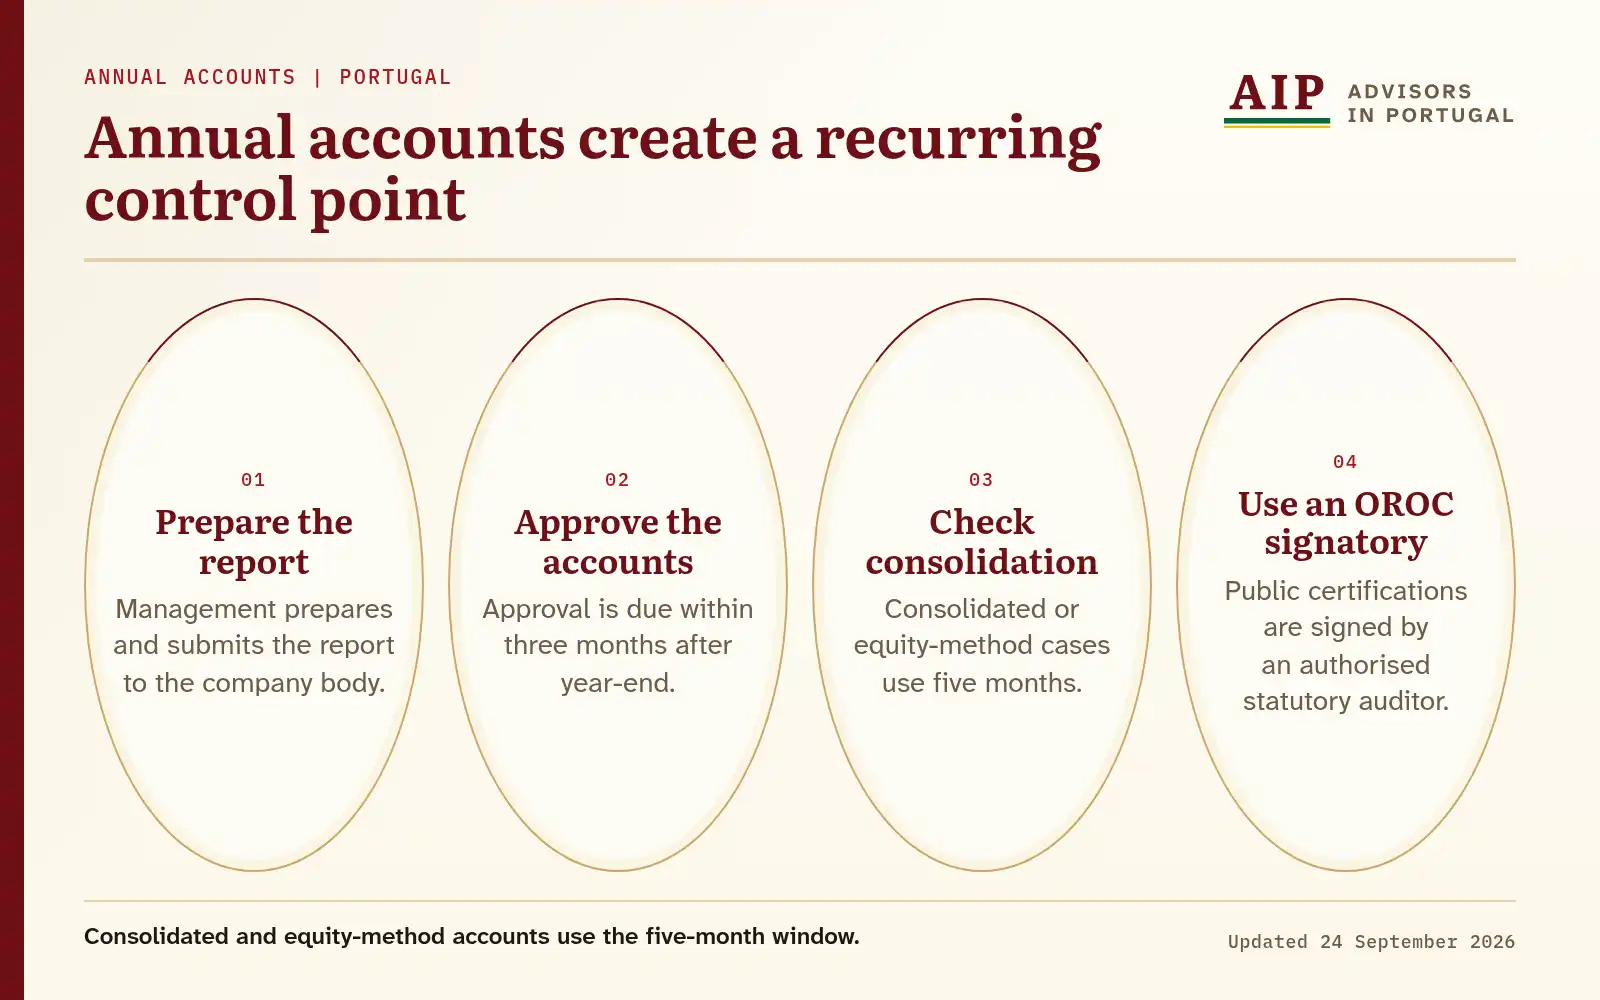
Diagram text version
Prepare the report. Approve it within three months. Use five months for consolidated cases. Use an authorised statutory auditor.
What Your Audit File Needs
- Entity and ownership chart
- Company form, shareholders, directors, subsidiaries, parent entities and public-interest status.
- Two-year threshold data
- Balance-sheet totals, net sales and other income, average employees and the prior two financial years.
- Accounting records
- Trial balances, ledgers, journals, supporting schedules, policies and SNC financial statements.
- Group consolidation file
- Control rights, subsidiary accounts, consolidation adjustments, exemptions and reporting perimeter.
- Governance and appointment records
- Board decisions, auditor appointment, independence confirmations, conflicts and engagement authority.
- Prior audit and registry file
- Earlier reports, management letters, commercial filings, correspondence and unresolved matters.
How an Audit Engagement Starts
The accounts and commercial-filing process is sequenced with the Conservatória do Registo Comercial, and OROC, tax, consolidation and governance questions are flagged along the way.
-
Map entity and group scope
You provide the company form, ownership, subsidiaries, public-interest status and reporting year.
-
Test the Article 262 threshold
A specialist compares the two-year figures with the statutory balance-sheet, income and employee thresholds.
-
Collect the appointment records
A specialist collects the appointment records the auditor asks for, including the appointment authority and the independence confirmations.
-
Build the SNC and consolidation file
The SNC and consolidation file covers accounting records, control evidence, consolidation adjustments and exemptions.
-
Prepare reporting and approval
The management report, accounts, audit report, approval and commercial registration are sequenced.
-
Close the audit record
The engagement file retains the evidence, signed reports, correspondence and unresolved items it requires.
Timing and Possible Delays
Set case by case
The work is planned around the entity count, year-end, group scope, accounting records and audit evidence.
What delays it
The work takes longer when ledgers are incomplete, group control is unclear, prior matters remain open or independence requires a different appointment route.
What to prepare now
You prepare threshold data, accounts, group records, governance decisions, prior reports and correspondence before the work begins.
Ongoing Audit Obligations
Threshold evidence and appointment
A specialist compares two years of balance-sheet, net-sales and employee data before the Article 262 conclusion is recorded. You provide ownership, public-interest, governance and prior-audit records before the OROC appointment is proposed. The statutory auditor confirms its independence and incompatibility position, and those confirmations are kept with the engagement authority on file.
Accounts, consolidation and filing
The management report, annual accounts, consolidation adjustments and audit report are sequenced before approval. You provide subsidiary ledgers, control evidence and exemption material where the group presents consolidated accounts. The approval record sits beside the commercial-registration steps.
Evidence retention and professional duties
Audit evidence, correspondence, signed reports and responsibility records are organized after the engagement scope is fixed. You provide access logs, explanations and unresolved items needed for the file. The Portuguese professional duties that continue during the engagement are recorded in the file.
Set out your audit requirement
Describe your entity, group, year-end, threshold figures and reporting questions.
Common questions
When is a statutory audit triggered in Portugal?
Are the SNC size categories the audit test?
Who can sign a statutory-audit report?
What independence rules apply?
When must annual accounts be approved?
When are consolidated accounts required?
Which accounting framework applies?
How long must audit files be kept?
How is an audit requirement handled?
How the Service Works
-
One team for the whole case.
The thresholds, accounts, group reporting, governance and registry questions that follow stay with one case team.
-
English or Portuguese.
English or Portuguese, whichever you are most comfortable in.
-
A written quote before work starts.
You get a quote in writing before any work starts. Fees are set case by case.
-
A clear answer on scope.
You are told plainly if a case falls outside the service.
What clients say about working with our founding team
Reviews from clients who worked with our founding team at their previous firm.
1–3 of 13
-
Samuel T. Google review, c. 2024 “I decided to partner with [the firm] for the establishment of multiple subsidiary companies in different jurisdictions. The entire process was streamlined and I felt well-supported throughout. I continue to collaborate with them in these countries and would highly recommend their services!”
-
Joseph V. Google review, c. 2016 “Our company has used the services of [the firm] for the purpose of conducting a thorough Due Diligence on a number of mining titles, the preparation of complicated, cross jurisdictional purchase contracts as well as the incorporation of a local subsidiary... All work was completed to a high standard, on budget and on time.”
-
Joe M. Google review, c. 2022 “Expanding our operations in Colombia has been challenging to say the least... Their years of experience, professionalism and most importantly their patience(!) have been vital to our success... [They] honestly feel like an extension of our team.”
-
Amy D. Google review, c. 2019 “The team at [the firm's Ecuador office] has helped streamline our accounting and other administrative tasks flawlessly between two countries and between staff and vendors in multiple locations... Highly recommended.”
-
Kunal D. Google review, c. 2022 “[The founder and the team] have always demonstrated a prudent, distinct and rapid ways of resolving issues and can tailor the needs as per our requirements... Their quick and error free approach has been instrumental.”
-
Julian A. Google review, c. 2022 “I emailed them and it was not more than a couple of hours when they emailed me back... I cannot be more satisfied with how [the firm] handled the process of registering my business in the country.”
-
George T. Google review, c. 2016 “The team is knowledgable, experienced and extremely professional, whilst being very approachable and friendly. If you want to do business in Mexico, there is no one better, in my opinion.”
-
Priscila O. Google review, c. 2024 “The group is fantastic! Contact [the founder] and the group if you require assistance with the incorporation of your small business!!!”
-
Christopher W. Google review, c. 2015 “I was pleased to find all the staff that worked with us to be not only attentive and responsive, but aware of our specific needs. Although we were unable to proceed due to our own financial situation, it did not stop [the firm], and more specifically... [the founder], from trying to find ways to make the effort work.”
-
Hassan J. Google review, c. 2024 “Very much appreciated the opportunity to speak directly with [the founder] when I reached out. The information provided was clear and in contact. Highly recommended!!!”
-
Simon T. Google review, c. 2020 “A great service. Very efficient. [The founder] was professional and organised everything we needed”
-
Janete C. Google review, c. 2024 “Thanks for everything... An excellent experience and highly recommended!!!”
-
Sean W. Google review, c. 2025 “[The founder] and Team [at the firm] provided our company quick, accurate & relevant advice to our company for a proposal in Costa Rica. Recommend their services to anyone...”
Text in [brackets] replaces names used in the reviews. The original reviews are on Google.
Contact us
Your request is in
Every request is read in house. The requirements are assessed, and a reply by email sets out the appropriate next steps.
Every enquiry is read in house, and the aim is a reply within one business day.
The information on this page is checked against official sources and reviewed regularly. It is corrected when the law or official guidance changes, as the Editorial Standards describe.